
Eric Sepanek
SBC Founder
Eric Sepanek is the founder of Scottsdale Bullion & Coin, established in 2011. With extensive experience in the precious metals industry, he is dedicated to educating Americans on the wealth preservation power of gold and silver.

Add SBC on Google as a preferred source to see more market related news like this when you search.


The United States is rapidly approaching $40 trillion in national debt right as the cost of servicing the debt reaches multi-decade highs. As federal deficits persist and investor confidence wanes, the market is demanding higher returns for government-issued securities.
Long-term Treasury yields, which determine the interest paid on government debt, recently hit multi-decade highs. This further increases the interest burden on the debt while expanding the pressure felt by the broader economy.
For precious metals investors, the setup is especially striking as gold remains historically strong even as bonds are paying more.
Long-Term Yields Spike as Investors Demand More
The national debt reached roughly $39.9 trillion this week, leaving the U.S. only about $100 billion away from the $40 trillion threshold, a stark milestone reflected in the nation’s climbing debt-to-GDP ratio. Although the raw debt total is mind-boggling, the more corrosive development is what Washington now has to pay in servicing costs.
Similar to any debt, the federal government pays interest on the securities it issues to attract buyers. With massive national borrowing, persistent inflation concerns, and rising fiscal uncertainty, investors are demanding greater compensation to lend Washington money over long periods.
Alarmingly, long-term Treasury yields are spiking to multi-decade highs as the case for holding U.S. assets is getting harder to defend.
- The 30-year Treasury yield recently climbed above 5.2%, near its highest level since 2007.
- A recent 10-year Treasury auction cleared near 4.68%, the highest auction yield for that maturity since 2007.
The U.S. government issues securities for various periods, from four weeks to several decades. However, the 10- to 30-year yields are widely considered benchmark rates because they reflect broad-based investor sentiment about the economy over an extended timeframe.
The Yield Curve is Steepening
The gap between short- and long-term Treasury yields offers another window into investor sentiment. Two-year Treasuries currently yield about 4.1%, compared with roughly 4.6% for 10-year securities and 5.2% for 30-year bonds.
That widening spread is creating a steeper yield curve, a closely watched measure comparing returns across different maturities. In practical terms, investors are demanding increasingly more compensation to lend the government money for longer periods, signaling greater concern about the long-term economic and fiscal outlook than the near-term picture.
Interest Costs Surge By 15%
Rising long-term Treasury yields increase the cost of servicing the national debt, as Washington faces higher rates when issuing new debt or refinancing maturing obligations. With roughly a quarter of outstanding Treasuries maturing in 10 years or longer, persistently high long-term rates could become increasingly costly as debt is refinanced.
The impact is already noticeable, with interest on the public debt on pace to hit $1.17 trillion this fiscal year, which represents a 15% jump from the same period last year. Notably, the fiscal year doesn’t end until September 2026, so this figure has a few more months to increase further. According to the Office of Management and Budget, servicing costs in 2026 are expected to reach a record $1.3 trillion.
Looking at how debt-servicing costs have evolved over the decades puts the scale of this increase into perspective.
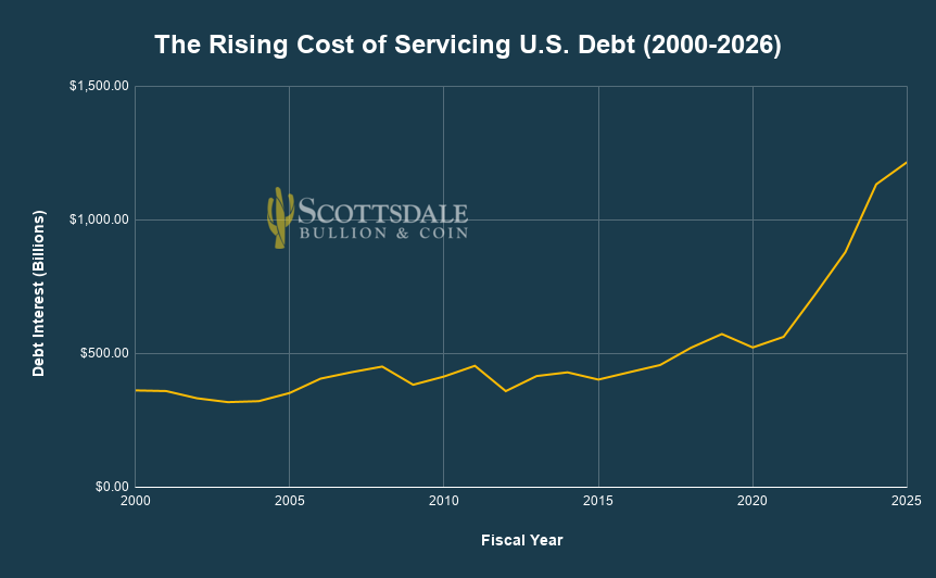
Over the years, debt interest payments have represented an increasing percentage of the annual federal budget. In 2025, this mandatory expenditure represented 14% of the federal budget.
This rising expense creates a dangerous feedback loop in which higher debt drives up interest costs, widens deficits, and requires even more borrowing, further increasing the cost of servicing the debt.
Gold’s Strength Signals a Changing Monetary Landscape
Typically, rising Treasury yields, especially across long-term securities, are a major headwind for safe-haven assets. Unlike some conventional assets, precious metals don’t offer guaranteed, recurring returns through dividends or interest payments. Thus, a high-interest-rate environment usually weighs on demand and valuations.
However, gold has remained remarkably resilient in the face of steadily rising Treasury yields. Even after entering a slight correction following an all-time high in January, gold prices remain well above $4,000/oz. This sharp divergence from the traditional relationship between yields and gold may reflect a broader shift in the monetary landscape.
That shift is increasingly visible in how central banks manage their reserves. Gold recently overtook the U.S. dollar and euro as a share of global foreign reserves by value. Over the next five years, 84% of central banks expect gold to account for a larger share of reserves, while 74% expect the dollar’s share to decline.
For investors watching this shift unfold, the question naturally turns to portfolio strategy, including how much gold should be in your portfolio.